
Asset Architecture: Optimizing Capital Velocity and Wealth Insulation
Stop accepting unmitigated downside. Discover how sophisticated capital allocators utilize an engineered asset wrapper to maintain high market exposure with near-zero downside potential
THE STRUCTURAL EDGE
This framework does not rely on traditional, stagnant risk models. Instead, it positions a specialized Indexed Universal Life (IUL) contract as a dynamic financial repository. By utilizing institutional index allocation options and adding strategic growth enhancements, your capital actively captures structural market upside while operating under a contractual floor designed to protect against absolute equity loss
THE THREE PRINCIPLE MECHANICS
Mitigated Market Exposure
Your underlying capital is not directly exposed to equity liquidation risk, keeping your baseline downside potential near zero percent. Instead, your strategy targets market upside through index performance tracking, combining active index options with custom growth multipliers to optimize upside potential
Historical Growth Replication
While future annual interest tracking can never be guaranteed or locked in prematurely, this specific asset class configuration—utilizing premium growth enhancements—has historically demonstrated an impressive 11% to 16% compounding yield over the past 50+ years throughout multiple economic cycles
Uninterrupted Opportunity Velocity
When secondary investment targets emerge, you do not liquidate your equity tracking account. By pulling highly efficient contractual loans directly against the contract value, your core cash reserve continues to run its growth tracking trajectory unhindered. Your capital works in two places at once
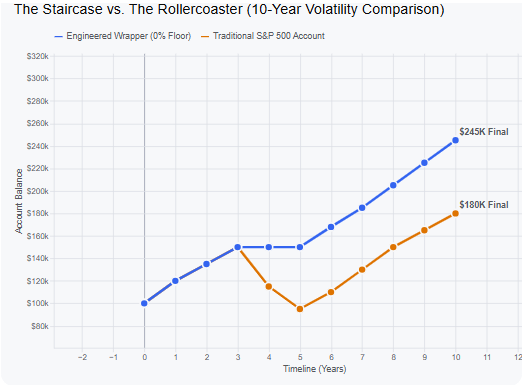
Visualizing the Floor: Wealth Preservation in Market Volatility
When you invest in a traditional S&P 500-based retirement account, you are subjected to unmitigated sequencing risk. A single down-market cycle can erase years of compounding, forcing your capital into a multi-year rescue mission just to get back to break-even
The Engineered Wrapper Strategy changes the mathematical rules of wealth accumulation. By leveraging a strict contractual floor, your capital behaves like a one-way staircase: you lock in market gains during growth years, and your balance flattens safely at zero when the market crashes. You never lose your principal, meaning your next growth cycle begins from a higher, protected baseline
STRATEGY COMPARISON OVERVIEW
Strategy Performance
(A) Traditional S&P 500 (IRA/Brokerage)
(B) The Engineered Wrapper
Up-Market Capture
(A) 100% Market
Participation
(B) Capped Index
Growth
(e.g., 10-12%)
Down-Market Impact
(A) Full Market Losses
(-30% to -40%)
(B) 0% Contractual
Floor
(No Losses)
Recovery Period
(A) 3 to 5 Years
to get back to even
(B) 0 Days
(Immediate
forward
compounding)
Tax Treatment
(A) Taxed at
withdrawal
or capital gains drag
(B) 100% Tax-Free
Distributions & Growth
Regulatory Disclosure: This documentation outlines a structural financial mechanism built on Indexed Universal Life (IUL) frameworks and does not represent an off-the-shelf consumer life insurance product. Principal is not legally insulated from loss. Past historical index performance tracking from the last 50+ years does not guarantee or explicitly project future contract interest credits. Growth is not locked in and varies based on capping rules, participation rates, and specific premium enhancement configurations
Crucially, when risk reduction becomes mandatory, the structural limitations of the traditional approach become even more glaring compared to the robust, predictable boundaries of an engineered wrapper
💡The True Cost of Capital (Tax Advantages)
Structural Tax Insulation: Keeping What You Engineer
Growth is meaningless if a changing tax landscape liquidates half of your purchasing power at harvest. The Engineered Wrapper utilizes statutory tax exemptions to build an ironclad perimeter around your wealth
- Tax-Free Accumulation (The Compound Engine): Unlike a standard brokerage account where dividends and rebalancing trigger annual capital gains taxes, capital inside the Wrapper compounds with zero tax drag. Every dollar saved on taxes remains in the engine to compound
- Tax-Free Distributions (The Exit Strategy): Traditional IRAs and 401(k)s carry a massive hidden liability: you are investing pre-tax dollars into a future tax rate that is completely unknown. The Wrapper allows you to access your wealth via structured contractual loans, providing 100% tax-free income during your distribution phase
- Tax-Free Wealth Transfer (The Legacy): When wealth passes to the next generation, traditional assets face income tax in respect of a decedent (IRD) and potential estate taxes. The Wrapper transfers cleanly to your beneficiaries as a tax-free death benefit, bypassing probate completely
🔍 The Ideal Candidate Checklist
Is This Strategy Engineered For You?
This framework is a specialized financial instrument designed for specific capital allocation goals. It is typically best suited for individuals who meet the following criteria:
- Significant Surplus Capital: You are maxing out standard tax-advantaged vehicles or looking for a home for $25,000+ annually in surplus liquidity
- Volatility Fatigue: You want market-linked indexing exposure but refuse to accept unmitigated downside market risk
- Liquidity Demands: You require high-velocity capital and want the ability to access cash tax-free for real estate or business opportunities without triggering penalties
Request Your Bespoke Asset Architecture Blueprint
Do not rely on generic calculators or static 12% projections. Let our team map your exact capital capacity against real-world historical indices. We will build a customized simulation showing your precise growth curve, tax savings, and contractual floor parameters